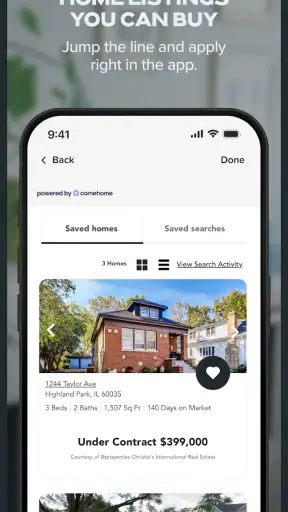
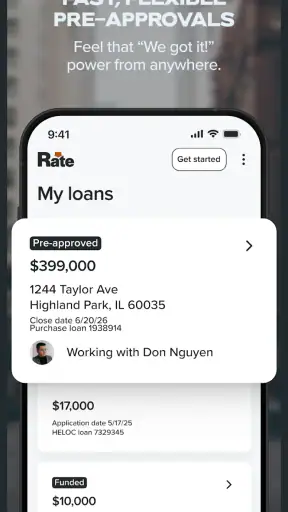
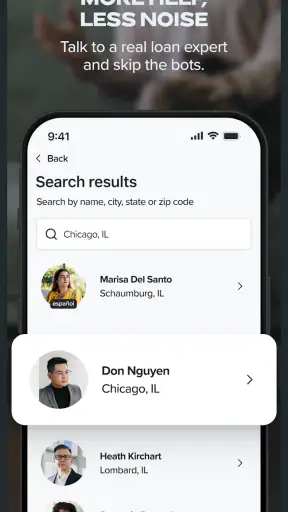
I approached Rate: Home, Finance & Wellness as a practical finance app rather than a single-purpose mortgage calculator. Its focus is unusually broad: home financing, refinancing, auto loans, home equity, personal loans, travel, and wellness all sit under one roof. That mix makes it interesting for people whose financial decisions overlap with everyday plans, but it also means the app is best understood as a starting point for exploring options, not as a complete replacement for every financial tool.
Developed by Guaranteed Rate, Inc, the free app is aimed at an Everyone audience and runs on Android 7.0 or later. It has built a solid public presence, with over 500 thousand installs and an average rating of 4.5 from around 1.9 thousand ratings. Those figures suggest that the app has found a useful place for many people, although popularity alone does not tell me whether it will suit a particular borrowing situation.
My overall impression is that Rate works best when I want to organize an early-stage financial decision. If I am thinking about buying a home, replacing a car, using home equity, or comparing the idea of refinancing, having related topics in one app is convenient. If I need a full budgeting system, detailed investment analysis, or an independent marketplace covering every lender, I would look elsewhere.
How Rate feels in everyday use
A broad starting point for major money decisions
The strongest part of this app is its range. Many finance apps force me to choose one narrow task, such as tracking spending or checking a credit score. Rate takes a different route by bringing several borrowing categories together. That is useful because real decisions rarely stay inside one neat box. A home purchase can affect transportation costs, a renovation can lead to a home-equity question, and a move can bring travel expenses into the same conversation.
I find this approach more helpful during the planning stage than during the final stage of a loan decision. The app can help me frame the question I am asking: am I looking for a mortgage, considering a refinance, investigating a personal loan, or trying to understand whether my home could support another project? That framing matters because choosing the wrong category at the beginning can send me toward the wrong comparison.
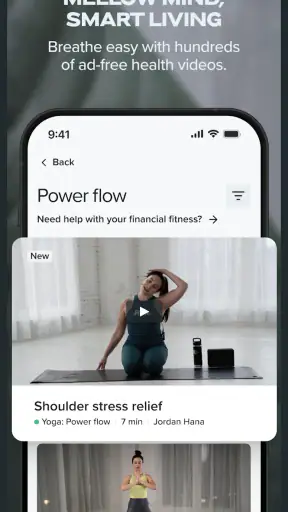
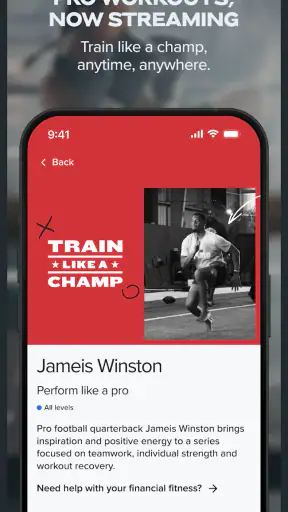
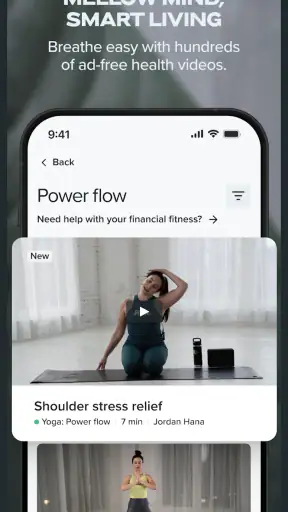
The travel and wellness elements make the product feel less like a traditional loan utility and more like a broader lifestyle companion. That may appeal to someone who wants financial topics and personal planning in one place. At the same time, users who prefer a focused mortgage experience may see those additional areas as distractions. I would decide based on how often I want one app to cover connected parts of my life.
Where it fits beside familiar alternatives
Compared with a bank app, Rate may feel more focused on exploring lending possibilities rather than managing an existing checking account. A bank application usually gives me direct access to balances, transfers, statements, and established accounts. Rate is more relevant when I am considering a new financial commitment or want to investigate a lending path connected to housing and personal plans.
Compared with a dedicated budgeting app, it is not the tool I would choose for categorizing purchases, setting detailed spending limits, or reviewing recurring expenses. A budgeting application is built around cash flow. Rate is built around larger decisions and the services surrounding them. The two types can complement each other, but they solve different problems.
Compared with a general loan marketplace, the experience may be more coherent because the categories are presented within one recognizable financial brand. The trade-off is that I would not treat one provider’s app as a complete survey of the market. For a major loan, I would still compare the terms, fees, repayment structure, and service offered by several sources before committing.
A realistic situation where it helps
Imagine I am considering a move while my current home still has value. I might first explore mortgage options for the next property, then think about whether refinancing or home equity is relevant to the present one. At the same time, I may need a personal loan for moving-related costs or a vehicle loan after relocating. Rate’s value in that situation is not that it makes the decision for me. Its value is that it gives me a single place to sort the questions before I start collecting formal offers.
I would use it in stages. First, I would identify the type of financing that matches the goal. Next, I would write down the information I need to compare elsewhere, such as the amount borrowed, estimated repayment period, total cost, and any conditions attached to the offer. Only after that would I treat an in-app option as something worth pursuing. This workflow prevents convenience from turning into an automatic decision.
What the current version tells me
The current version is listed as 1.52-prod. I see that as a useful sign that the app is being maintained as a live product rather than left as a one-time release. It was released on May 11, 2023, so its development history is still relatively recent compared with long-established finance platforms.
Those facts help set expectations, but they do not tell me that every part of the experience has changed recently or that the app will behave identically on every device. I would keep the application updated through the normal app-store process, especially when using finance software, because current releases are generally the sensible place to look for compatibility and reliability improvements.
Changes and product direction
The available release information confirms the present version and the original release point, but it does not provide a detailed change log that I can responsibly turn into a list of new functions. I would not claim that a particular calculator, dashboard, notification system, or application workflow was added in a specific update without clear evidence.
What I can say is that the product direction is visible in its combination of lending categories with travel and wellness. That is a deliberate expansion beyond a conventional mortgage tool. For new users, the effect is a wider first impression. For existing users, the important question is whether the additional areas improve their routine or make it harder to reach the financial task they opened the app to complete.
In my view, the best evolution for an app with this scope would be better separation between its major purposes. A person researching home equity should be able to concentrate on that task without feeling pushed through unrelated lifestyle material. Someone interested in wellness should not have to navigate a dense lending experience first. Clear organization is more important here than simply adding more sections.
What existing users may notice
People who already use Rate for housing or borrowing topics may appreciate having more subjects available without installing a separate application. That convenience is especially relevant for users who return during different life stages. A mortgage question today can become a refinance question later, while a home project can lead to a personal-loan decision.
The possible downside is attention. A broader app can become less direct if every category competes for space. I would judge an update by how quickly I can return to the task I started, not by how many menu options appear. For existing users, a smoother route to familiar sections would matter more than a larger collection of headlines or promotional prompts.
There is also a practical habit I recommend: after an update, revisit the app’s navigation before beginning a serious application. Confirm that you are in the intended product area and that the figures or terms you are reviewing relate to the right type of loan. This is a small step, but it is valuable when several financial products sit close together.
Three ways I would use it more intelligently
First, I would use Rate as a question-organizing tool. Before opening it, I would write one sentence describing the goal: buying, refinancing, borrowing against a home, financing a vehicle, or covering a personal expense. That simple preparation makes it easier to recognize whether the information in front of me actually answers my question.
Second, I would separate exploration from commitment. I might use the app to learn which lending category seems relevant, but I would keep a separate note with competing offers and the full repayment cost. The most attractive headline figure is not always the cheapest choice once duration, fees, and conditions are considered. The app is most useful when it supports comparison rather than replacing it.
Third, I would treat the travel and wellness areas as planning companions, not proof that I can afford a larger loan. A trip, treatment, or lifestyle goal can be a legitimate reason to review finances, but it should not automatically justify borrowing. Keeping the personal goal separate from the lending decision helps me avoid turning a convenient in-app path into unnecessary debt.
Where the experience may fall short
The biggest limitation is scope. Rate covers many subjects, but breadth can never guarantee depth in every one of them. Someone who wants advanced household budgeting, investment monitoring, tax preparation, or comprehensive credit education will probably need specialized tools alongside it.
I also would not use it as my only source for a high-value financial commitment. A loan is not merely a button inside an app. It involves eligibility, documentation, repayment risk, and terms that deserve careful reading. Even if the app makes the first steps feel simple, I would still verify the complete offer and ask questions before agreeing to anything.
Another possible friction point is the relationship between convenience and independence. Because the app comes from Guaranteed Rate, Inc, users who want a neutral, multi-provider comparison may prefer a service designed specifically for broad market shopping. That does not make Rate unsuitable; it simply means I would be clear about the role it plays in my research.
People who dislike lifestyle content inside finance products may also want a more focused alternative. If I only need to monitor spending or manage an existing bank account, I would choose a dedicated budgeting or banking app. Rate makes more sense when housing, lending, and related personal planning are active concerns.
Questions I would ask before installing
Will it replace my bank app? No. I see it as a companion for exploring financial products and related topics, not as a universal account-management center. I would keep my regular banking application for daily transactions and use Rate when a larger borrowing or planning question comes up.
Is it suitable for someone buying a first home? It can be a useful place to begin organizing the mortgage conversation, especially if the user is still learning which housing-finance path fits the situation. I would not let a first-time buyer rely on it alone. A beginner still needs to understand the full cost of ownership, compare providers, and review every document carefully.
Can an existing homeowner benefit from it? Yes, particularly when the question involves refinancing, home equity, or another loan connected to a property. The practical benefit is the ability to consider related routes in one environment. The important caution is to compare the long-term effect of changing a loan, not just the immediate payment or advertised rate.
Is it a good choice for a small, everyday expense? That depends on the purpose. If I am trying to understand a personal-loan option, it may be relevant. If I simply need to track groceries, subscriptions, and monthly bills, I would use a budgeting tool instead. Rate is aimed at decisions that require research, not routine expense entry.
Will older phones support it? The stated minimum is Android 7.0, so devices running that system or a newer one meet the listed operating-system requirement. I would still keep the phone’s software current where possible, particularly when handling financial information, and I would expect the smoothness of the experience to vary with the device.
What I would watch as the app develops
For a product with this many themes, I would watch whether the navigation becomes more purposeful over time. The key test is simple: can I reach a mortgage, refinance, auto, home-equity, or personal-loan task quickly, while travel and wellness remain easy to find without taking over the financial experience?
I would also look for clearer support around comparison and decision-making. Users benefit when an app helps them understand the difference between an initial possibility and a final obligation. Explanations that encourage checking total cost, repayment length, and conditions would add more value than a larger collection of loosely connected topics.
Finally, I would pay attention to how existing users experience version changes. The current 1.52-prod release shows an active product line, but the meaningful measure for me is whether updates preserve familiar workflows while making them clearer. A finance app should feel dependable first and expansive second.
My recommendation
I recommend Rate: Home, Finance & Wellness to people who are actively exploring housing finance, refinancing, vehicle loans, home equity, or personal borrowing and would like related subjects gathered in one free app. Its Everyone rating and support for Android 7.0 or later make it approachable for a wide audience, while its established install base and 4.5 average suggest that many users find the concept worthwhile.
I would skip it if my main goal is detailed budgeting, investment management, or completely provider-neutral loan shopping. In those cases, a specialized alternative will usually give me a clearer and deeper experience. I would also avoid treating it as a shortcut around financial research. The app can help me start the conversation, but it cannot remove the need to compare and understand the final terms.
After using it as a broad planning companion, I see its real strength in connecting several major decisions that often appear together in real life. Its weakness is the same thing: covering many areas can make focus harder. Used deliberately, with a written goal and an independent comparison of final offers, Rate: Home, Finance & Wellness is a useful first stop for borrowing research, not the last word on what I should choose.


